Malaysia is introducing e-Invoicing through the MyInvois System, aiming to modernize how businesses record and validate transactions. This guide explains e-Invoicing, self-billed invoices, and how businesses in Malaysia can comply with the new rules.
What is an Invoice?
An invoice is a document issued by a seller to a buyer to list goods or services and payment details. With e-Invoicing, invoices become digital and machine-readable, in formats like XML or JSON, and are validated by the Inland Revenue Board of Malaysia (IRBM).
Types of E-Invoices
- Standard Invoice
- Definition: Issued by the seller.
- Example: A wholesaler selling office supplies to a company issues an e-Invoice listing items, quantities, and terms.
- Self-Billed Invoice
- Definition: Created by the buyer when the seller cannot issue invoices.
- Example: A tenant pays rent to a landlord who is not running a business and issues a self-billed invoice for tax compliance.
- Credit Note
- Definition: Corrects errors or adjusts overcharges without refunds.
- Example: If a retailer receives fewer items than ordered, the supplier issues a credit note to adjust the bill.
- Debit Note
- Definition: Adds charges to a previous invoice.
- Example: A logistics company charges extra storage fees by issuing a debit note.
- Refund Note
- Definition: Records the return of payments.
- Example: A store refunds a customer for a defective product and issues a refund note.
Benefits of E-Invoicing
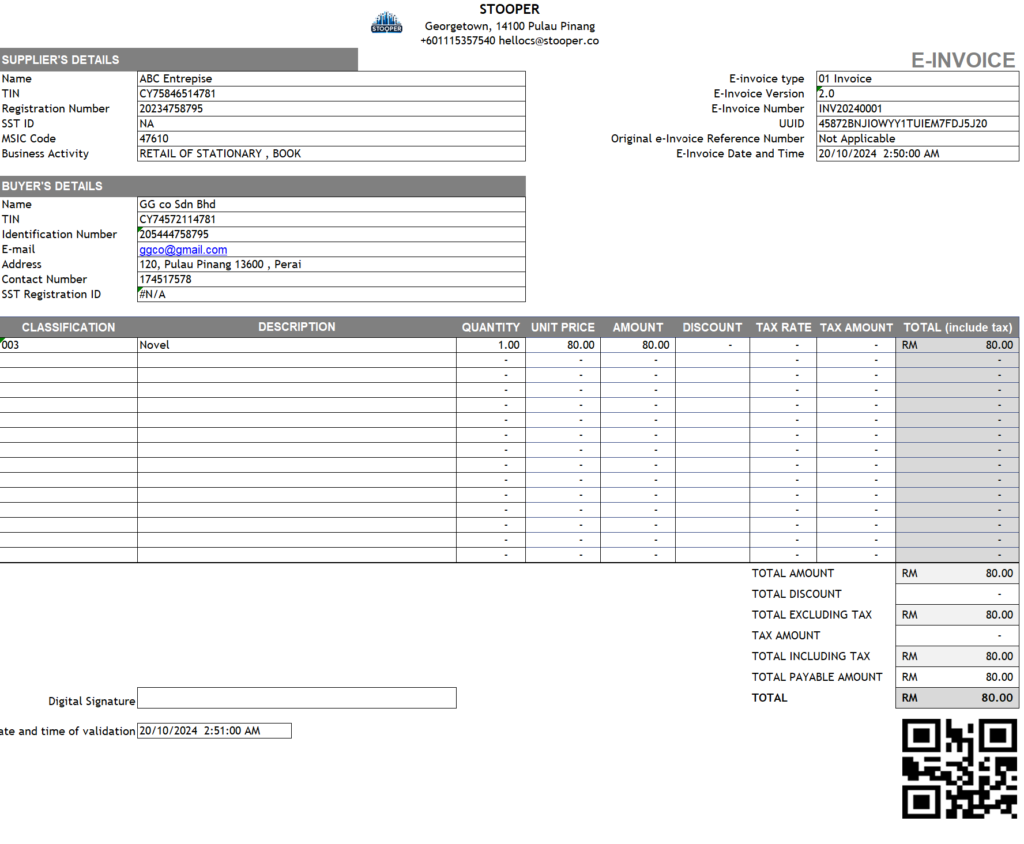
- Compliance: Mandatory under phased implementation by IRBM.
- Accuracy: Reduces errors with structured formats.
- Transparency: Real-time validation ensures invoice legitimacy.
- Efficiency: Speeds up processes and reduces paperwork.
Self-Billed Invoices
What are they?
Self-billed invoices are issued by buyers for specific transactions, like paying rent to non-business landlords or dealing with suppliers unable to provide invoices.
When to Use Them?
- Rent payments to non-business landlords.
- Importing goods/services where the supplier doesn’t issue E-invoices.
- Transactions with rural suppliers lacking internet access.
For Importing Goods from Overseas:
When importing goods from suppliers overseas, businesses should issue a self-billed invoice if the supplier does not provide an invoice. Ensure that the customs form code and HS code are included in the e-Invoice to comply with customs and tax regulations.
Revising E-Invoices
How long can e-Invoices be revised?
E-Invoices can be canceled and replaced within 72 hours of validation by IRBM. After 72 hours, adjustments require credit notes, debit notes, or refund notes.
Example:
A business realizes an overcharge on an e-Invoice. If caught within 72 hours, they cancel the invoice and issue a corrected one. Beyond 72 hours, they use a credit note to adjust the amount.
Key Steps for Businesses
- Understand the Rules: e-Invoices are required for both local and cross-border transactions.
- Prepare Systems: Use the MyInvois portal or integrate APIs for seamless e-Invoice handling.
- Submit Timely: Consolidated invoices must be submitted within seven days after month-end. Errors should be corrected within 72 hours.
- Include Customs Form Code and HS Code for Imports: For imported goods, businesses must key in the relevant customs form code and HS code when issuing e-Invoices to ensure compliance with customs and tax regulations.
Malaysia’s e-Invoicing system simplifies tax compliance and enhances transparency. By understanding the various types of invoices, self-billing, and revision timelines, businesses can adapt to the new system with ease and stay compliant with IRBM requirements.
For more information about E-Invoice : Official Guildelines of E-Invoice on LHDN
For more blog : Stooper's Business Talk